

Ditch: Pay Off Debt Faster

- 62.00 Reviews
- 4.8
- Downloads
- 10,000+
Our take on Ditch: Pay Off Debt Faster from Appgk
Debt is easy to treat as a vague problem until several balances, due dates, and interest charges start competing for attention. I found Ditch: Pay Off Debt Faster most useful as a focused finance app for turning that mess into a visible payoff plan. It does not try to be a complete banking replacement. Instead, its appeal is the narrowness of its purpose: helping me organize what I owe and keep the act of repayment in view.
That focus gives the app a clear identity, but it also sets the right expectations. If you want a full budget, investment dashboard, or bank account manager, this is not the tool I would put first. If your main struggle is knowing which debt to tackle, tracking progress, and staying consistent after the initial motivation fades, Ditch is much easier to recommend.
How Ditch turns debt into a practical routine
The app comes from Ditch Technologies, Inc and sits in the finance category. It is free to install, with optional in-app purchases ranging from $5.99 to $89.99 per item. That combination makes it approachable for someone who wants to test the basic experience before deciding whether extra paid functionality fits their situation.
What I like about the concept is that it moves the conversation away from “I owe too much” and toward a sequence of decisions. A debt payoff tool is valuable when it helps answer ordinary questions: What should I pay first? How much progress have I made? What happens if I add a little more? The usefulness is not in making debt disappear magically; it is in making the next action less ambiguous.
Best Parts of Ditch: Pay Off Debt Faster
Things to Keep in Mind About Ditch: Pay Off Debt Faster
That distinction matters because many people already know they should spend less and pay more. The difficult part is maintaining a system when rent, groceries, subscriptions, and unexpected costs interrupt the plan. Ditch’s payoff-centered approach gives those users a dedicated place to return to instead of leaving the plan scattered across notes, calculator results, and memory.
A realistic month with the app
Imagine someone with a credit card balance, a personal loan, and a store financing account. Their income arrives twice a month, while the debts have different minimum payments and due dates. Without a central plan, they may make every minimum payment but still feel unsure whether they are making meaningful progress.
News and Features Related to Ditch: Pay Off Debt Faster

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
I would use Ditch at the beginning of the month to review the balances, decide how much extra money is genuinely available, and identify the account that deserves the additional payment. After payday, I would check the plan again rather than relying on a hopeful estimate. At the end of the month, the important habit would be recording the result and comparing it with the previous position.
The subtle benefit of this workflow is psychological as much as mathematical. A debt balance can feel static when it is only seen on a statement. A payoff tracker gives the user a reason to notice small reductions. That can help prevent the common cycle of making one ambitious payment, losing track of the plan, and returning to the problem only when another bill arrives.
Don't want to read the full review?
Where its payoff focus is strongest
The strongest case for Ditch is someone who has enough information to begin but lacks structure. You do not necessarily need advanced financial knowledge to benefit from a clear payoff sequence. In fact, the app makes more sense for a beginner who wants a manageable process than for a person already maintaining a detailed spreadsheet with formulas, scenarios, and custom categories.
I also see value for people who share financial goals without wanting to merge every part of their finances. A couple, for example, could use the same payoff logic when discussing which balance to prioritize, while still keeping their everyday spending accounts separate. The app can serve as a conversation anchor: instead of arguing from anxiety, both people can look at the same repayment objective.
Screenshots
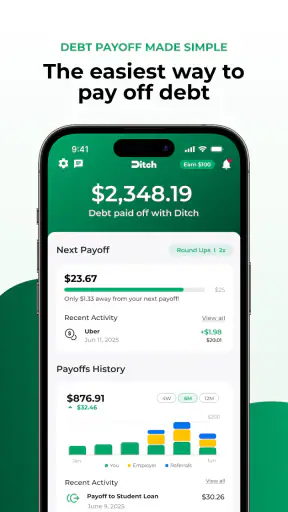
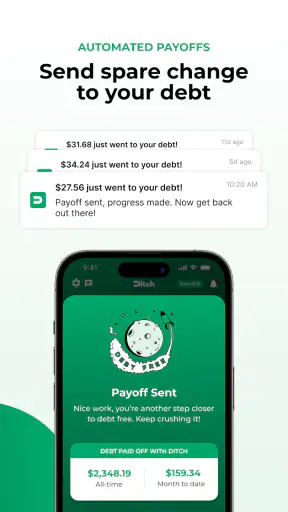
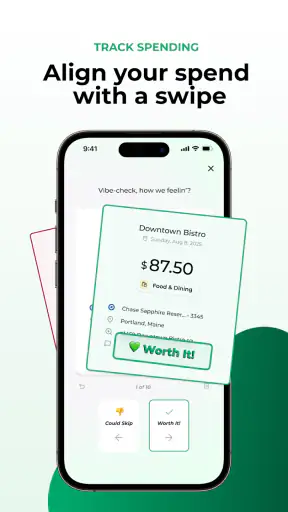
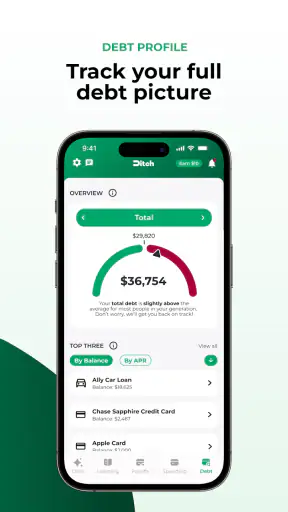
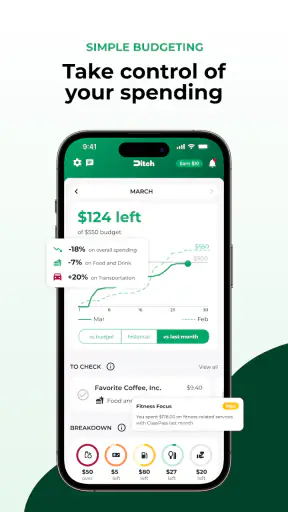
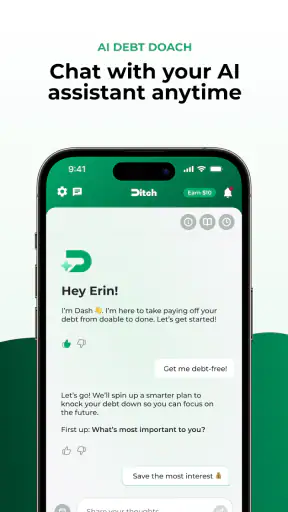
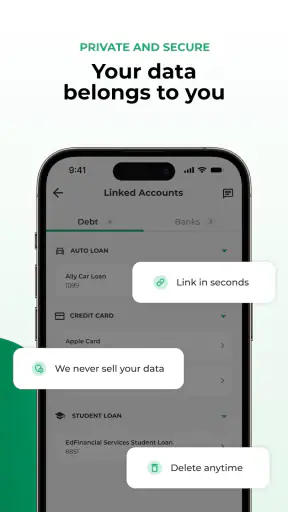
Another useful habit is to review the plan before making discretionary purchases. I would not use that as a way to turn every coffee into a guilt exercise. I would use it for larger choices, such as delaying a nonessential purchase until an extra payment is made. Seeing the trade-off in the context of a specific debt can make the decision more concrete than a general budgeting rule.
The most important strength is behavioral clarity: Ditch keeps the payoff goal visible enough to support repetition, not just a one-time burst of motivation.
Practical ways to get more from the tracker
My first tip is to enter debts carefully and treat the initial setup as a financial inventory, not a rushed formality. The quality of any payoff plan depends on the balances, minimums, and terms being accurate. If you guess because a statement is nearby but unread, the resulting plan may look reassuring while being based on the wrong starting point.
My second tip is to separate a planned extra payment from money that is merely possible. A strong month may allow an unusually large payment, but building a routine around that amount can create frustration when expenses return to normal. I would choose a sustainable baseline and treat windfalls or unusually low spending as occasional accelerators.
Third, I would review the app after any major change rather than waiting for a monthly ritual. A new bill, a changed income pattern, or a paid-off account can alter the order or pace of repayment. The tracker is most useful when it reflects the current situation, not when it becomes a historical record that no longer guides decisions.
A less obvious trade-off is the difference between a mathematically efficient plan and a motivating plan. Some users prefer to attack the highest-cost debt first because it can reduce interest over time. Others gain momentum by clearing a smaller balance early. Ditch can help keep the chosen approach visible, but the user still has to decide which priority fits their temperament and financial details. A tracker supports judgment; it does not replace it.
What the app does not replace
I would not treat Ditch as a substitute for checking official lender statements. The app can organize a repayment strategy, but the lender remains the source for the amount currently owed, the minimum due, and the payment deadline. Before sending money, I would compare the plan with the account itself, especially after interest or fees have been added.
I would also keep a separate emergency buffer in mind. Paying debt faster is attractive, but sending every available dollar toward balances can leave a household exposed to the next repair, medical expense, or income interruption. The right payoff pace is not always the most aggressive one. Ditch is helpful for showing the debt objective, but it cannot decide how much financial breathing room your life requires.
That limitation is important for users expecting automatic answers. The store summary presents the app as a way to automate payoff and track debt, but automation should not be confused with handing over every financial decision. I would still verify transfers, review payment dates, and make sure a planned amount will not overdraw an account. A useful plan becomes harmful if it is followed mechanically without regard to cash flow.
People with complicated obligations may also outgrow a focused tracker. If your situation includes tax debt, collections, legal judgments, variable-rate loans, or several household incomes, a specialist adviser or a more comprehensive financial system may be the better choice. Ditch can improve organization, but it should not be mistaken for debt counseling or a negotiated repayment service.
Who should choose Ditch
I think Ditch is a good fit for someone who has multiple debts and wants one clear place to monitor the path forward. It is especially appealing if spreadsheets feel intimidating, if you repeatedly lose track of balances, or if motivation disappears after the first payment. The app’s narrow purpose can be an advantage because it avoids burying the payoff goal under unrelated financial screens.
It may also suit a person who has tried a general budgeting app and found that spending categories did not solve the real problem. Budgeting tells you where money went; a payoff tracker keeps attention on what remains. The two approaches can work together, with a budget controlling available cash and Ditch organizing the repayment target.
I would be more cautious about recommending it to someone with only one simple debt and a reliable payment routine. In that case, the lender’s own account tools, a calendar reminder, or a basic note may be enough. Adding another app is useful only when it reduces confusion or improves consistency. If it merely duplicates information you already manage comfortably, the extra step may not justify itself.
I would also hesitate if you want investment tracking, detailed household budgeting, bill negotiation, or a broad financial overview in the same place. Ditch’s value comes from its debt focus, so users searching for an all-in-one money center should compare it with a broader alternative before committing to a paid option.
Everyday friction and the paid decision
The free entry point is a sensible way to judge whether the workflow fits your habits. I would spend time using the core tracking process before considering an in-app purchase. The important question is not whether a premium option sounds useful in theory, but whether it changes your behavior enough to justify the cost.
Because individual items can cost from $5.99 to $89.99, the range is wide enough that I would read each purchase screen carefully and avoid assuming that every user needs the most expensive choice. A debt app should reduce financial stress, not encourage an impulsive purchase made from financial anxiety. I would only pay for something that clearly supports my own repayment routine.
There is also a maintenance cost that no app can eliminate. Balances change, payments clear at different times, and real life rarely follows a perfectly smooth schedule. If you dislike updating financial information or reviewing plans, Ditch may feel like another obligation. Its best results depend on a small but repeated commitment from the user.
On the technical side, the app supports devices running Android 8.0 or later. It is rated for Everyone, which makes the presentation broadly accessible, although an age rating should not be confused with financial suitability. A young user or a person sharing finances with family may still need guidance when deciding how much to pay and which obligations take priority.
What its current reception suggests
Ditch has an average rating of 4.8 from around 1.1 thousand ratings, with more than sixty written reviews, and it has passed over ten thousand installs. Those figures suggest that the focused idea is connecting with a meaningful early audience, while the written review volume remains small enough that I would avoid treating the rating as a complete picture of every possible use case.
The app was released on September 12, 2023, and the current version is 1.5.6. I mention that context because financial tools benefit from ongoing attention: users need confidence that the app remains usable as their circumstances change. Before relying on it for an important repayment routine, I would still explore the current interface and make sure it handles the type of debt tracking I need.
Those details do not change my central view. A high rating can encourage a trial, but it cannot replace checking whether the app matches your habits. Someone who wants a simple, debt-first workflow may appreciate the same focus that disappoints someone looking for a complete personal finance suite.
My verdict after looking at the whole experience
Ditch: Pay Off Debt Faster is at its best when debt feels disorganized rather than impossible. I like its direct purpose, its invitation to turn repayment into a repeatable routine, and the way a dedicated tracker can make progress easier to notice. The free starting point lowers the barrier to testing that approach, while the optional purchases mean users should make a careful value judgment before spending more.
I would recommend it to a person with several balances, inconsistent motivation, and a genuine desire for a clearer payoff path. I would not recommend relying on it alone for complex financial decisions, emergency planning, or official payment verification. Those responsibilities remain with the user, the lenders, and, when necessary, qualified financial professionals.
My final advice is simple: install it only if you are willing to review your debts honestly and return to the plan regularly. Used that way, Ditch can become a practical accountability tool rather than another forgotten finance download. If you already have a reliable spreadsheet or need a full money-management system, a different option may serve you better. For the person who mainly needs debt to become visible, ordered, and actionable, this app makes a convincing case for itself.
Ditch: Pay Off Debt Faster FAQ
What is Ditch: Pay Off Debt Faster, and how does it work?
Ditch: Pay Off Debt Faster is a personal finance app designed to help you organize debts, understand repayment progress, and build a clearer plan for becoming debt-free. After entering relevant balances, interest rates, minimum payments, and other details, the app can help you review your situation and track payments over time. It is primarily a planning and monitoring tool, not a lender or debt settlement service.
Can Ditch help me pay off credit cards, loans, or other types of debt?
The app is intended for people managing common forms of consumer debt, such as credit cards, personal loans, and similar balances. Its usefulness depends on the information and account types supported in the current version. Before relying on a particular feature, check the app’s description and settings to confirm whether your debts can be added manually or connected through an available integration. Always verify calculations against your lender’s statements.
Does Ditch automatically make payments or connect directly to my bank accounts?
Ditch should not be assumed to make payments on your behalf. Apps in this category generally focus on budgeting, repayment planning, reminders, and progress tracking, while actual payments still need to be completed through your bank, card issuer, or loan provider. If the app offers account connections, review the permissions carefully and confirm whether the connection is read-only, what data is accessed, and how it can be disconnected.
Is Ditch: Pay Off Debt Faster free to use?
Availability of free features, subscriptions, trials, or optional in-app purchases may vary by platform and change over time. Before downloading or starting a trial, review the pricing page in the App Store or Google Play and read the subscription terms carefully. Pay particular attention to renewal dates, cancellation requirements, and whether advanced planning, synchronization, or reporting tools require payment. Avoid entering sensitive financial information until you understand the cost.
Is Ditch safe to use for managing personal debt information?
Because debt details are sensitive, you should review Ditch’s privacy policy, security information, and requested permissions before using it. Use a strong, unique password if an account is required, enable device security, and avoid sharing screenshots containing balances or account numbers. The app can support better organization, but it does not replace professional financial advice. If you have serious financial difficulties, consider speaking with a qualified nonprofit credit counselor or financial adviser.











